Dollar Stays Down Ahead of CPI
Monthly CPI Due
The US Dollar remains weak today ahead of the keenly awaited monthly October CPI readings this afternoon. Interestingly, the market is looking for core CPI to cool from 0.3% to 0.2% and headline to drop from 0.6% to 0.3%. Given the rise we saw in annualised data and the general strength of US data recently, particularly last week’s NFP release, expectations for a decline seem disjointed here, particularly given that energy prices rebounded over the last month and have remained elevated. As such, we could be in for an upside surprise in today’s inflation data which, if seen, should help revived USD strength as December tightening expectations.
December Rate-Hike Expectations
The market is currently pricing in a roughly 80% chance of a hike by year end, up from around 70% pre-NFP last week. As such, there is still plenty of room for a further strengthening of expectations which should help USD find its feet again. On the other hand, if the data confirms the expected decline today, this could muddy the outlook somewhat leading to a softening of December tightening forecasts. Still, given the backdrop of very strong jobs data, higher energy prices and hawkish Fed speak (Waller voiced his support this week for a further hike), USD should resume its upward trend before long regardless of today’s data.
Technical Views
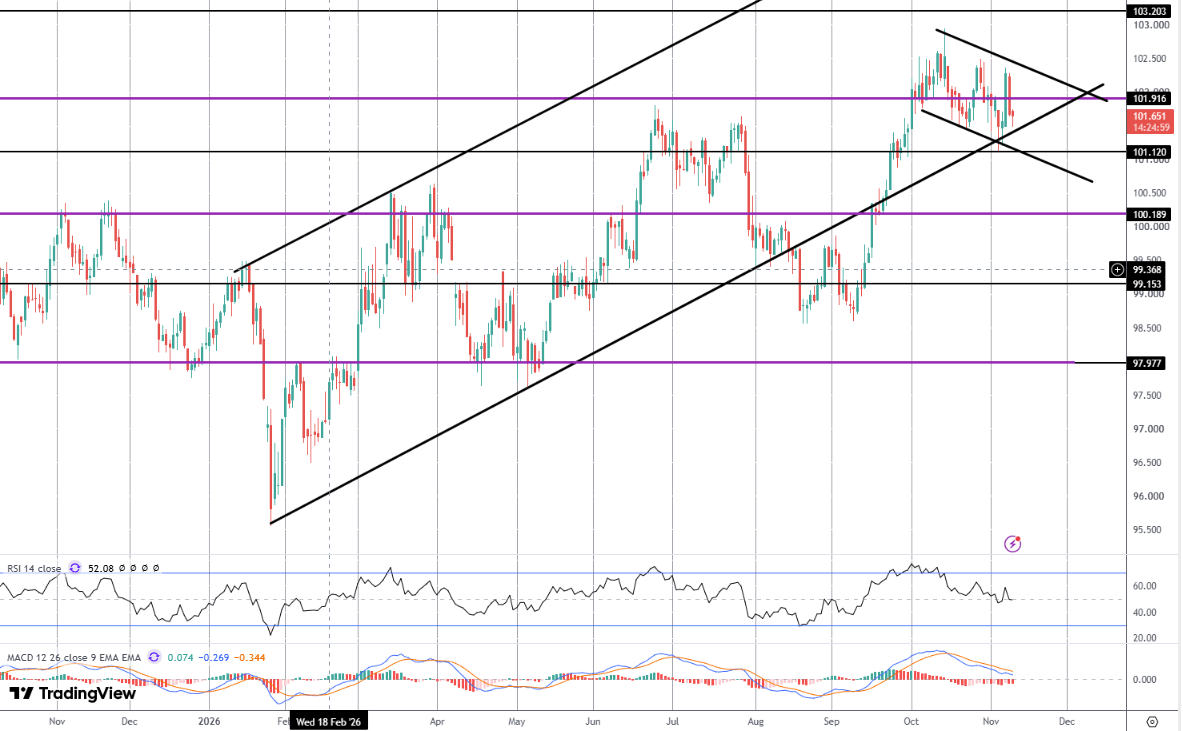
DXY
For now, the index remains supported by the bull channel lows, keeping the focus on an eventual return to upside. However, while 101.91 caps, risks of a break lower are seen and if we breach the 101.12 support and bull channel lows, focus turn back to the key 100-level next.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
With 10 years of experience as a private trader and professional market analyst under his belt, James has carved out an impressive industry reputation. Able to both dissect and explain the key fundamental developments in the market, he communicates their importance and relevance in a succinct and straight forward manner.