FTSE Caps Volatile Week with Gains
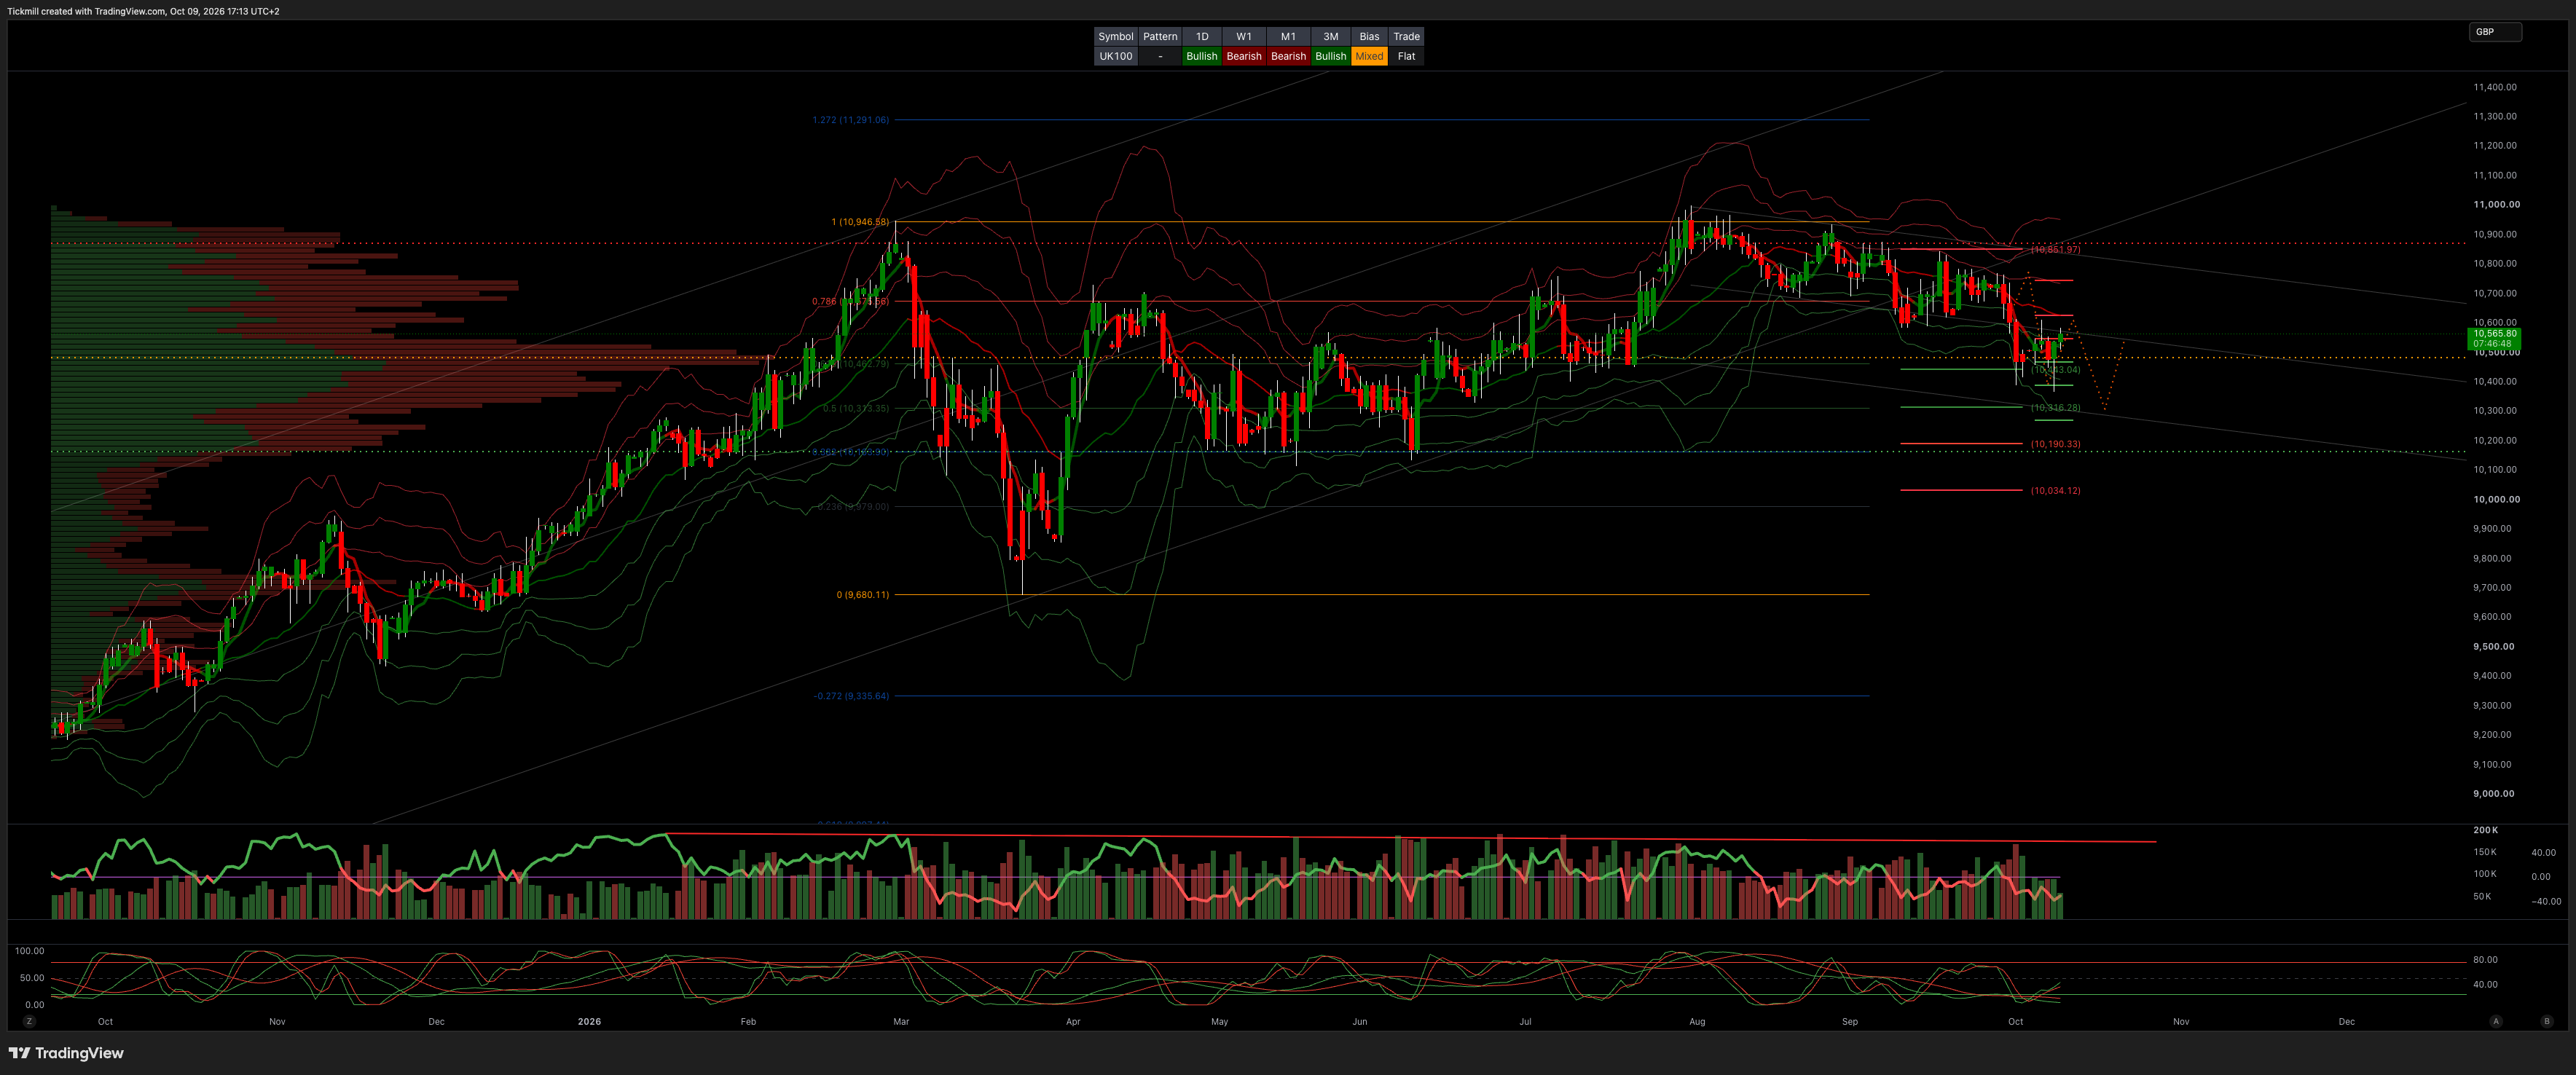
FTSE Caps Volatile Week with Gains as Easing Oil and Yields Boost Mining and Tech
London shares rose on Friday as easing oil prices and a retreat in gilt yields lifted market sentiment, allowing the benchmark FTSE 100 to close up 19.80 points, or 0.19%, at 10,557.00 GBP. The rally helped U.K. indexes cap a volatile week with modest overall gains, recovering from earlier multi-month lows as geopolitical anxieties in the Middle East temporarily abated.
Mining, technology, and professional service heavyweights heavily concentrated the gains. Rebounding metals prices lifted major resource names, with Antofagasta climbing 3.9%, Fresnillo advancing 3.3%, and Glencore rising 3.1%. Anglo American Plc gained 2.9%, Endeavour Mining added 2.3%, and Rio Tinto rose nearly 1.5%. Technology and analytical software counters saw strong buying interest: The Sage Group surged 4.2%, RELX gained 4.1%, and Experian advanced 3.7%. Broad-based strength across 3i Group, Weir Group, ConvaTec Group, ICG, London Stock Exchange Group (LSEG), Croda International, Howden Joinery, St. James's Place, Computacenter, IMI, and Smith & Nephew generated additional 2% to 3% upside. Further support came from Haleon, Halma, GSK, Next, Informa, Diageo, Marks & Spencer, Aberdeen Group, British Land, and Burberry Group. On the FTSE 250, Morgan Advanced Materials jumped 8.7% following an RBC Capital upgrade after selling its Thermal Products unit.
Telecoms, energy majors, and select leisure names faced persistent downside pressure. Telecom providers were hit hard after SpaceX agreed to acquire a nationwide portfolio of low-band spectrum licenses, paving the way for Starlink Mobile to become a major U.S. operator. Consequently, Airtel Africa dropped 5.4%, Vodafone Group fell 4.0%, and BT Group lost 2.5%, making them the session's worst top-flight performers. In market debuts, Airtel Money (AMCA) opened flat in London at £1.96, matching its oversubscribed offer price. Energy majors Shell, BP, Ithaca Energy, and Centrica drifted lower as crude retreated. Mid-cap Upper Crust owner SSP Group fell 4% after trimming its annual operating profit expectations.
Macro sentiment improved significantly as crude oil prices pulled back. Front-month Brent crude futures fell 1.26% to $102.97 a barrel after U.S. President Donald Trump stated Washington would not launch military strikes against Iran prior to next month's U.S. midterm elections, describing ongoing discussions with Tehran as productive. Fixed income markets mirrored the risk-on shift, with U.K. 10-year and 30-year Gilt yields easing after reaching multi-decade highs earlier in the week.
n the UK, resilience on the surface masks growing household strain. Bank of England credit data reveals rising demand and defaults across unsecured loans and credit cards as higher energy caps and living costs bite. Key UK data releases include monthly GDP and production figures on Thursday. Finally, central bank officials gather at the IMF annual meetings in Bangkok, with heavy commentary expected from Fed and BoE speakers ahead of the upcoming blackout window.
Finish Line: U.K. equities ended a turbulent week on a firm note as diplomatic pause signals in the Middle East cooled crude oil prices and relieved bond market stress. Strong performance across miners and tech heavyweights offset a direct hit to telecom operators from SpaceX disruption fears, restoring market stability into the weekend.
Disclaimer: The material provided is for information purposes only and should not be considered as investment advice. The views, information, or opinions expressed in the text belong solely to the author, and not to the author’s employer, organization, committee or other group or individual or company.
Past performance is not indicative of future results.
High Risk Warning: CFDs are complex instruments and come with a high risk of losing money rapidly due to leverage. 68% and 74% of retail investor accounts lose money when trading CFDs with Tickmill UK Ltd and Tickmill Europe Ltd respectively. You should consider whether you understand how CFDs work and whether you can afford to take the high risk of losing your money.
Futures and Options: Trading futures and options on margin carries a high degree of risk and may result in losses exceeding your initial investment. These products are not suitable for all investors. Ensure you fully understand the risks and take appropriate care to manage your risk.
Patrick has been involved in the financial markets for well over a decade as a self-educated professional trader and money manager. Flitting between the roles of market commentator, analyst and mentor, Patrick has improved the technical skills and psychological stance of literally hundreds of traders – coaching them to become savvy market operators!